Aged Care Business Interruption Insurance

Caring for the elderly is a deeply meaningful and essential service – but it also comes with significant responsibility. Whether you're an individual caregiver, a team of healthcare professionals, or operate a residential facility, having comprehensive insurance is vital to protecting your team, your clients, and your reputation.


At ACS Financial, we offer tailored insurance solutions for aged care facilities, workers, and providers across Australia. Our policies are designed to cover the complex risks that come within this sector – giving you peace of mind while you focus on delivering compassionate, professional support.


WHAT YOU NEED TO KNOW

Aged Care Insurance: Tailored Solutions for your
aged care facilities around Australia


This sector requires specific insurance policies that protect people, property, and the unique risks associated with elderly care. Whether you're running a facility or working as an individual provider, we offer comprehensive insurance options to suit your needs.

Types of Aged Care Insurance
available to you:


1. Public Liability Insurance for Aged Care Facilities

Public liability insurance is essential in aged care settings. It covers claims resulting from injury or property damage that may occur during the course of care, whether in a residential facility or during in-home visits.

Person holding an injured hand in a black brace while discussing compensation options with a lawyer in a professional setting.

Why Public Liability is Important

Elderly clients are more vulnerable to slips, trips, and accidental injury. When accidents happen, public liability insurance ensures that your business or facility is protected from the financial consequences of legal action.
This type of insurance for aged care facilities also reinforces your commitment to providing safe, professional care – something that gives residents and their families added confidence.

What Public Liability Typically Covers:


Injury to Residents or Visitors

Coverage for medical expenses and legal claims if a resident or guest is accidentally injured.

Damage to Client or Third-Party Property

Protection for incidents where staff accidentally damage belongings or premises.

Legal Defence Costs


Financial support for legal representation, even if you’re found not at fault.

Accidents in Common Areas

Whether in dining halls, gardens, or shared spaces, you’re protected from claims arising from everyday incidents.

Food or Medication-Related Incidents

Protection against claims arising from allergic reactions or mishandling of food or medication.

Injuries During Off-Site Outings

Coverage for incidents that occur during supervised outings or transport services, such as community visits or medical appointments.

Need insurance for your facility?


2. Professional Indemnity Aged Care Worker Insurance

Professional indemnity insurance protects workers and providers against claims of negligence, breach of duty, or errors in professional care.

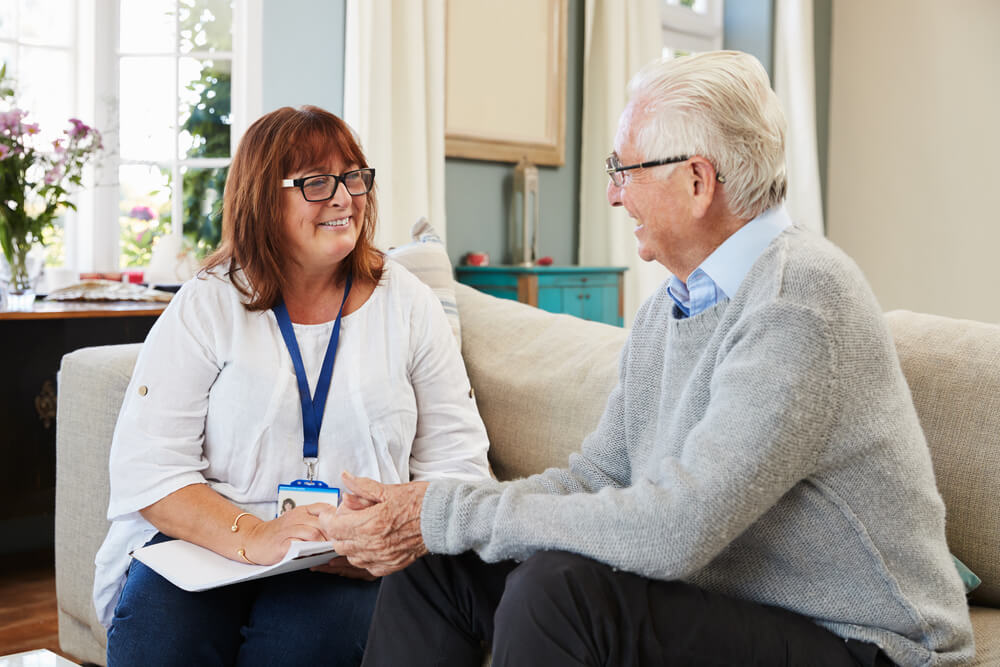
Aged care worker engaging with elderly client in a comfortable setting, highlighting professional care and communication essential for aged care services.

Why Professional Indemnity Matters

Aged care professionals manage complex medical, emotional, and physical needs. Despite best efforts, mistakes can happen – whether it’s a missed medication dose, a documentation error, or a miscommunication with a family.


Aged care worker insurance helps mitigate the financial and reputational risks associated with such claims, ensuring your focus remains on delivering excellent care.

What Professional Indemnity Insurance Covers:


Claims of Negligence or Inadequate Care

Coverage for allegations of improper care, delayed response, or medical oversights.

Incorrect Advice

Protection against claims arising from unintentionally providing inaccurate health, care, or treatment advice that results in harm or adverse outcomes for residents or their families.

Breach of Professional Duty

Protection if you're accused of not meeting standards or failing to follow policies.

Loss of Records or Documentation

Covers legal risks associated with the misplacement or loss of critical client files.

Breach of Confidentiality

Shields against unintentional data leaks or privacy violations.

Defamation and Libel

Covers legal action stemming from unintended verbal or written statements.

Protect your team and your reputation.

3. Personal Accident Insurance for Aged Care Workers

Aged care roles are physically demanding and emotionally taxing. Personal accident insurance provides protection for workers who may be injured on the job, from lifting residents to slips during shifts.

Aged care worker assisting elderly person, hands clasped, highlighting personal connection and support in caregiving.

Why Personal Accident Insurance is Vital

Whether you're a facility employee or a sole trader providing in-home care, you are your greatest asset. Personal accident insurance ensures you’re financially supported if you’re injured or become unwell, and unable to work.

What This Insurance Typically Covers:


Loss of Income Due to Injury or Illness

Compensation for missed wages, ensuring stability while you recover.

Medical & Rehabilitation Costs

Covers hospital stays, recovery treatments, emergency medical transport, and rehabilitation expenses.

Permanent Disability or Death Benefit

A lump sum payout for the worker or their family if serious injury or death occurs.

Want to safeguard your livelihood?

4. Additional Insurance Options for Aged Care Facilities

ACS Financial offers comprehensive cover across all levels of aged care services. Whether you run a small residential home, a large facility, or provide in-home support, these extra policies provide added protection:

Management Liability Insurance

Protection for directors, board members, and managers from risks like employment disputes, OH&S issues, or regulatory breaches.

Property Insurance for Aged Care Facilities

Covers damage to physical locations, such as aged care residences, medical equipment, and common areas.

Equipment Breakdown Insurance

Covers the cost of repair or replacement of essential equipment in case of malfunction.

Business Interruption Insurance

Helps facilities manage income loss due to temporary closures, fires, or other unexpected disruptions.

Volunteers Accident Insurance

Protects volunteers assisting within your facility from injury-related costs.

Cyber Liability Insurance

Protection against data breaches, cyberattacks, and accidental exposure of sensitive resident or medical information.

Are you looking for Aged Care Insurance?

Why Providers Benefit from Insurance

Why Aged Care Providers Need Insurance

Confidence in Care


With the right aged care insurance, your organisation and staff are protected from the unexpected. It allows you to focus on caring for elderly Australians without the worry of legal or financial consequences.

Woman smiling on phone while using laptop, representing support and communication in aged care insurance services.
Three women smiling in an office setting, representing a supportive environment for aged care providers, highlighting professionalism and trust in care.

Improved Credibility and Trust


Working with aged care insurance brokers like ACS Financial shows your commitment to quality and safety. Families and residents feel more secure knowing you have professional protection in place.

Essential Financial Protection


Insurance prevents one-off incidents from becoming long-term financial burdens. It’s an essential safety net for individuals and organisations providing elderly care.

Wooden figurine standing on a block, surrounded by upright wooden blocks and a toppled block structure, symbolising stability and support in aged care insurance.

But can you really trust us?

Here what our clients are saying:


Need help choosing the right insurance package?

Learn more about Aged Care Business Interruption Insurance

Decision-makers often need more than confirmation that a policy exists, as compliance requirements can place pressure on organisations managing risks across people, services, contracts and day-to-day operations. They need to know whether the arrangement reflects how the organisation actually operates, what obligations apply and the circumstances that could lead to a claim or dispute. There’s also added difficulty in figuring out complex language, and few organisations want to dedicate time to untangling what is and isn’t within scope. At ACS Financial, we have over 30 years of experience in refining tailored insurance and protection solutions for organisations. Because relevant considerations differ from one environment to the next, our guidance is shaped accordingly. So, rather than offering broad recommendations, we assess the operating realities, risks, obligations and activities that shape each organisation’s needs. NDIS providers are one example, coordinating workers across homes, community environments and multiple locations while adhering to demands of structured regulatory frameworks. We also work with businesses that want to safeguard their reputation and customer trust as they deliver specialised advice or professional services, and that’s where indemnity cover plays a key role. Whether you’re researching ‘aged care business interruption insurance’ or ‘business interruption insurance‘, a detailed assessment gives leaders practical guidance based on how their organisation actually operates.

The insurance your organisation requires depends on its operations, the assets underpinning its work, the people it interacts with, and where potential claims or interruptions sit. That’s why ACS Financial assesses these factors with you before recommending suitable cover, and as specialist brokers, we can even access insurance and protection products that insurers only offer through brokers. Where your operations carry a risk of accidental personal injury or property damage, you can turn to public liability protection options. These arrangements may be useful for NDIS workers visiting clients in their homes, childcare operators with responsibility for children, and other organisations that regularly engage with contractors, suppliers, clients, visitors or members of the public. There’s also professional indemnity insurance, which may cover certain legal defence costs and claims alleging that advice or professional services caused loss through an error, omission or negligent act. Meanwhile, for those who want cover that may protect assets against theft, public liability, property damage, glass breakage, machinery malfunction and other insured events, you could choose among options for commercial property insurance. Whether you’re considering protection solutions related to ‘aged care business interruption insurance’, ‘business interruption insurance construction‘ or ‘business interruption insurance cost‘, our goal is to recommend options that reflect your current operations and can adjust as your responsibilities change.

Choosing insurance requires clarity on what’s covered, what may have been missed and how each option aligns with your organisation’s obligations. You can gain clarity about these factors through a simple process that starts with a consultation where you can describe your particular situation. With your situation outlined, you can then address your objectives, existing arrangements and potential exposure while identifying what may help mitigate your risks. Following that, your information and needs are assessed against the insurance options that are available through the relevant network. From there, you get a quote and receive recommendations online, giving you a clear view of the proposed options before deciding whether to proceed. Your protection can begin once you’ve approved the quote. Across every stage, you can expect clear explanations and practical advice to help you assess which option fits your organisation’s needs or learn more about matters like ‘building Public Liability insurance‘ and ‘business insurance contents‘. And if you have questions about ‘commercial insurance for businesses chinchilla‘ or ‘daycare insurance cost‘ or require further guidance, you can speak with a specialist about your circumstances and enquiries. Learn more about your insurance and protection options now by speaking with a specialist.
DO YOU HAVE ANY QUESTIONS?

Frequently asked questions


What type of insurance do aged care facilities need?

At a minimum, facilities should have public liability, professional indemnity, and property insurance. Management liability and equipment breakdown cover are also highly recommended.


Is aged care worker insurance mandatory?

It is strongly advised to have public liability and personal accident insurance. This protects both the worker and their clients.


What’s the difference between public liability and professional indemnity?

Public liability deals with third-party injuries or property damage. Professional indemnity covers claims of negligence, errors, or failure to meet professional standards.


Do aged care providers need separate insurance for volunteers?

Yes. Volunteers should be covered under a separate personal accident policy to ensure they’re protected while working on-site or in-home care.


How much does aged care insurance cost?

The cost varies depending on your role, the size of your operation, services offered, and coverage needs. Our brokers can provide you with a tailored quote.


Can I get aged care insurance as a sole trader?

Absolutely. ACS Financial offers aged care worker insurance options specifically for sole traders and in-home providers.


Where can I find aged care insurance brokers I can trust?

ACS Financial is a leading broker for aged care insurance solutions in Australia. Our experienced brokers can guide you through your options to find the perfect policy.

ARE YOU READY TO START?

Get Aged Care Provider Insurance by clicking the button below: